GST Input Tax Credit Part 2
01eKTP 21
02Incidental exempt financial supplies
Incidental exempt financial supply is a supply of financial services made by a registered person who is not in the business of making the financial services. However, such person can treat input tax attributable to the exempt financial supplies as input tax attributable to taxable supplies.
This means that the registered person is entitled to claim any input tax that is attributable to the making of the exempt financial supplies
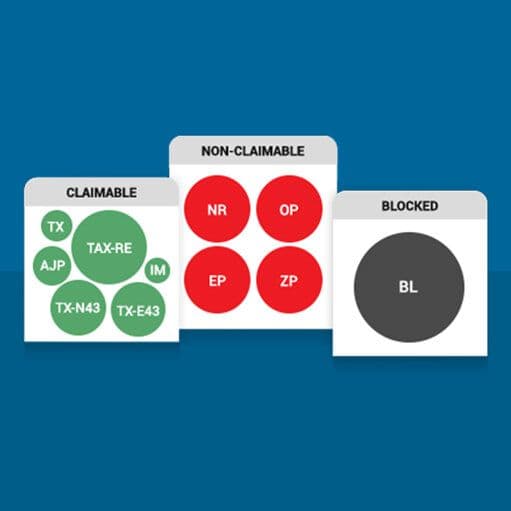
Tax code used : TX-E43
03How to claim INPUT TAX
GST cannot be claimed on goods and services which are not used for business purposes (e.g. for private use).
Where goods are used partly for business and partly for non-business purposes, the GST incurred is normally apportioned.
In order to claim input tax, a registered person must hold proper documents.
04Documents Needed in Claiming Input Tax
Input tax incurred can be claimed if the recipient is a registered person. The recipient must hold a tax invoice in respect of a supply of goods or services.
05Tax invoice
There are two types of tax invoices i.e. simplified tax invoice and full tax invoice.
A simplified tax invoice is only valid for claiming of input tax if the tax amount
does not exceed RM30. If the tax amount is more than RM30, the recipient has to request the supplier to include his name and address on the invoice.
A full tax invoice must be issued under the name of the registered person to be eligible for input tax credit. A tax invoice issued under the name of any person other than the registered person will not be eligible for input tax credit except for mobile phone bill expenses used for business purposes.
A registered person can use the mobile phone bill expenses invoice billed to his employee for claiming input tax as long as the expenses are reimbursed and accounted as business expenses.
The GST amount should be shown on the tax invoice; otherwise the registered person is not allowed to claim input tax using the tax invoice.
06Importation of good/service
In respect of importation of goods, the importer must hold a valid Customs importation document Customs No.1. In respect of clearance of goods from bonded warehouses, the importer must hold Customs No.1 or No.9.
For importation of services, the recipient is required to hold a document such as the foreign supplier’s invoice to show that he is entitled to claim input tax.
Tax code used : TX, IM
07Input tax not claimed
Any amount paid or to be paid in respect of goods and service tax (GST) as input tax by a person is not allowed as a deduction of Income Tax
- If he is liable to registered under GST Act but he has failed to do so.
- if he is entitled to the input tax credit under GST Act but has failed to claim.
Tax code used : UC
Come say hello.
Two firms in the heart of Taman Molek, Johor Bahru.
KTP & Company PLT
Wisma KTP, 53, 53-01 & 53-02, Jalan Molek 1/8, Taman Molek, 81100 Johor Bahru, Johor, Malaysia